Foreign-invested companies (PT PMA) in Indonesia must take note of a major tax overhaul. The government has officially enacted Peraturan Pemerintah Number 20 of 2026 (PP 20/2026), effective April 22, 2026. This new regulation strictly amends the previous rules (PP 55/2022) concerning the 0.5% Final Income Tax (PPh Final) scheme.
While this regulation is heavily aimed at MSMEs, it carries critical compliance implications for corporate structures, joint ventures, and tax planning strategies utilized by foreign investors.
Why PT PMAs Need to Pay Attention
Historically, some investors incorporated small-scale corporate entities, such as local Perseroan Terbatas (PT) or partnered with local commanditaire vennootschaps (CV), to leverage the simplified 0.5% final tax rate on gross turnover under IDR 4.8 billion.
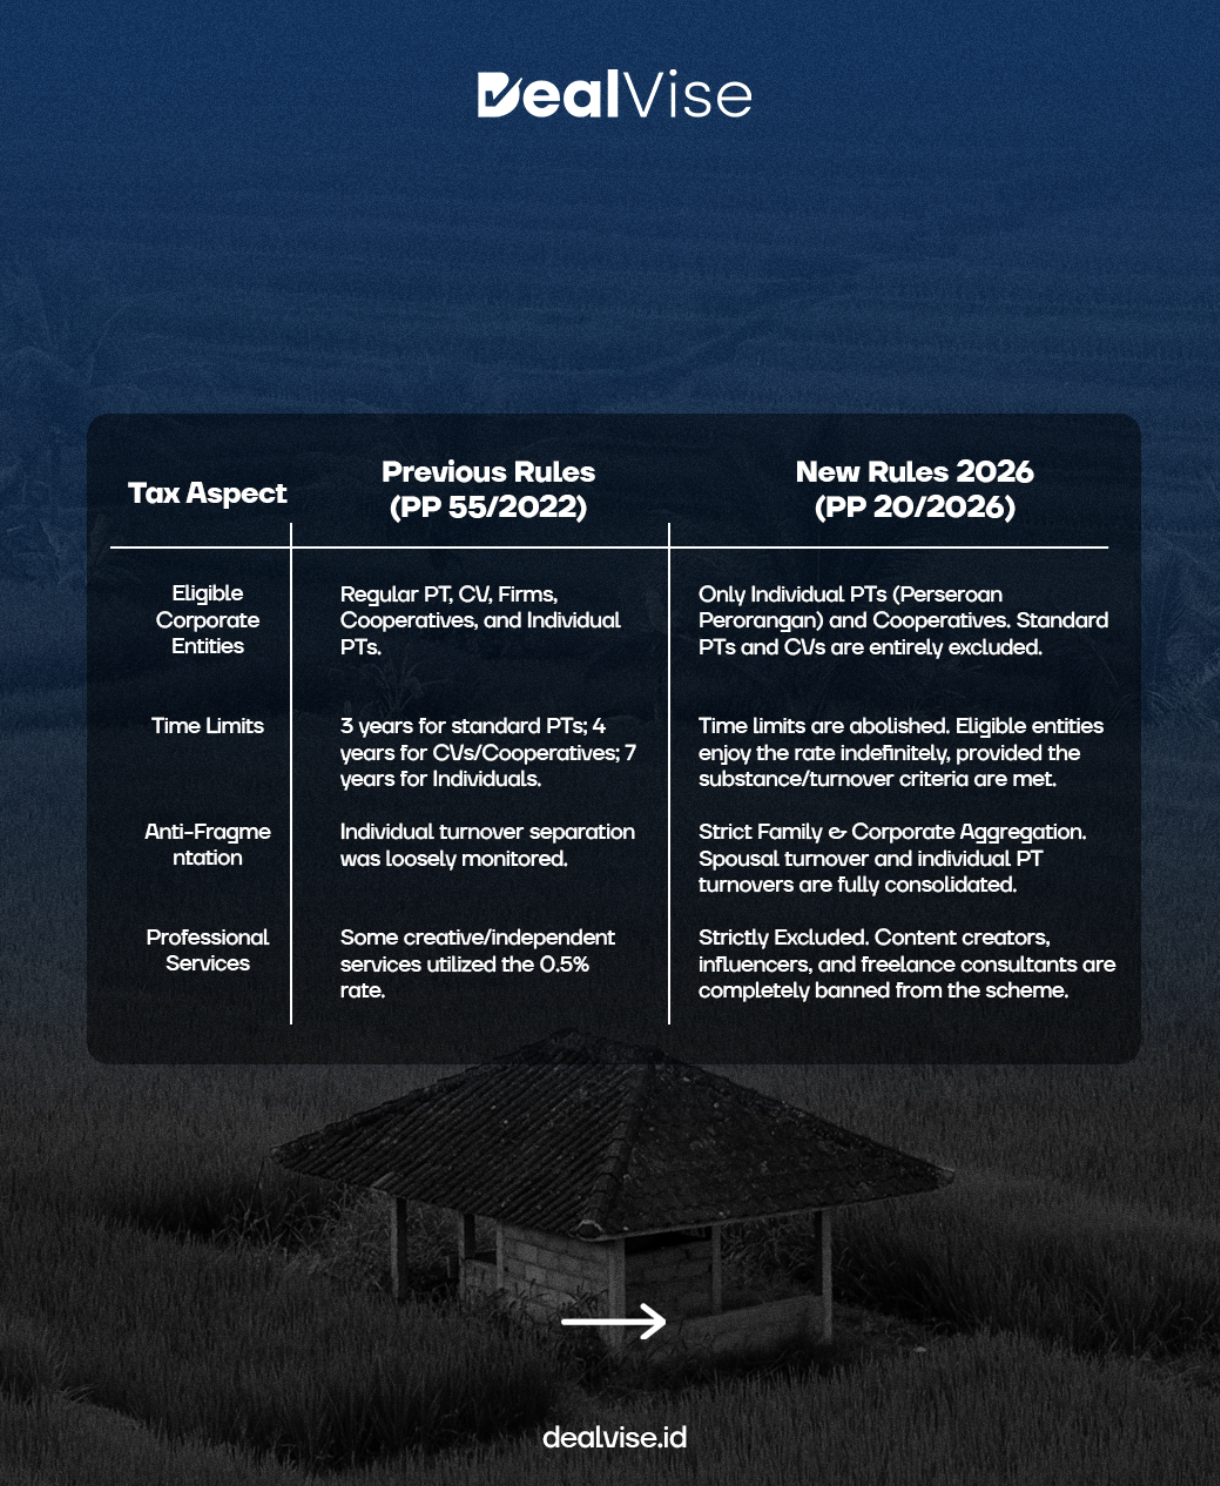
PP 20/2026 completely closes this loophole. The government’s new policy explicitly shifts from a time-based threshold to a strict, substance-based evaluation to prevent tax avoidance through corporate fragmentation.
Key Regulatory Changes in 2026
The new regulation narrows down the eligible entities for the 0.5% tax rate and implements aggressive anti-avoidance parameters.
Strategic Implications for Foreign Investors
If you are operating or structuring a business in Indonesia, you must adjust to the following impacts:
- New PTs & CVs Fall Directly Under Corporate Income Tax
Any standard limited liability company (PT, including PT PMA) or partnership (CV) registered after April 22, 2026, cannot apply for the 0.5% Final Tax rate—even if their revenue is well below IDR 4.8 billion. They are automatically subject to the normal Corporate Income Tax (CIT) regime under Article 17 of the Income Tax Law.
2. Transition Rules for Existing Corporate Entities
If you currently operate or partner with a local entity (PT/CV) that was utilizing the 0.5% tax scheme prior to April 22, 2026, a grace period applies:
- You may continue using the 0.5% rate only until your original facility period expires (e.g., the maximum 3-year allowance for standard PTs or 4 years for CVs from their registration date).
- No extensions will be granted. Once the transition period lapses, the company must migrate to standard bookkeeping and CIT rates.
3. Aggregation Risks & Coretax System Tracking
The Indonesian Directorate General of Taxes (DGT) is utilizing its advanced Coretax System to target tax arbitrage—the practice of splitting a large company into multiple smaller entities to stay under the IDR 4.8 billion threshold. Under PP 20/2026, the tax authority will trace the Beneficial Owners (BO). If multiple small entities or an individual family structure’s combined global revenue exceeds IDR 4.8 billion, the 0.5% facility is instantly revoked for all associated setups.
This scheme is now strictly restricted to Individuals and Single-Person Companies (Perseroan Perorangan), meaning that any foreign-invested entity (PT PMA) or corporate partner registered after this date must immediately switch to full corporate accounting. Furthermore, the regulation closes tax avoidance loopholes by consolidating the revenue tracking of spouses and all associated individual businesses, meaning that splitting operations into smaller entities to stay under the IDR 4.8 billion threshold will trigger automatic tax audits and forced system migration.